The California Housing Bond Trap: Who is Prop 37 Really Built For?
If you lived through the reckless era of “stated income” and no-doc mortgages leading up to the 2008 financial crash, the latest policy out of Sacramento should send a cold chill down your spine. California’s newly approved $25 billion housing bond initiative—marketed as a lifeline for middle-class homebuyers looking to bypass private mortgage insurance (PMI)—is being heralded as an affordability breakthrough.
As any seasoned real estate broker or veteran investor will tell you, when the state starts engineering financial engineering experiments to help buyers into homes with virtually zero skin in the game, it’s rarely about helping the public. It’s about bailing out homebuilders stuck with bloated inventory. And when the music stops, guess who’s left holding the bag? That’s right: the California taxpayer.
Let’s break down the mechanics of how this program works, why it mirrors the worst habits of the subprime era, and why it poses a massive systemic risk to the state’s financial stability.
The California Housing Bond Trap
How the Program Works: The 17% Piggyback Trap
On paper, the pitch sounds innocent enough: help middle-class families escape the dreaded monthly cost of Private Mortgage Insurance (PMI) by providing a state-backed second mortgage.
Here is how the machinery operates:
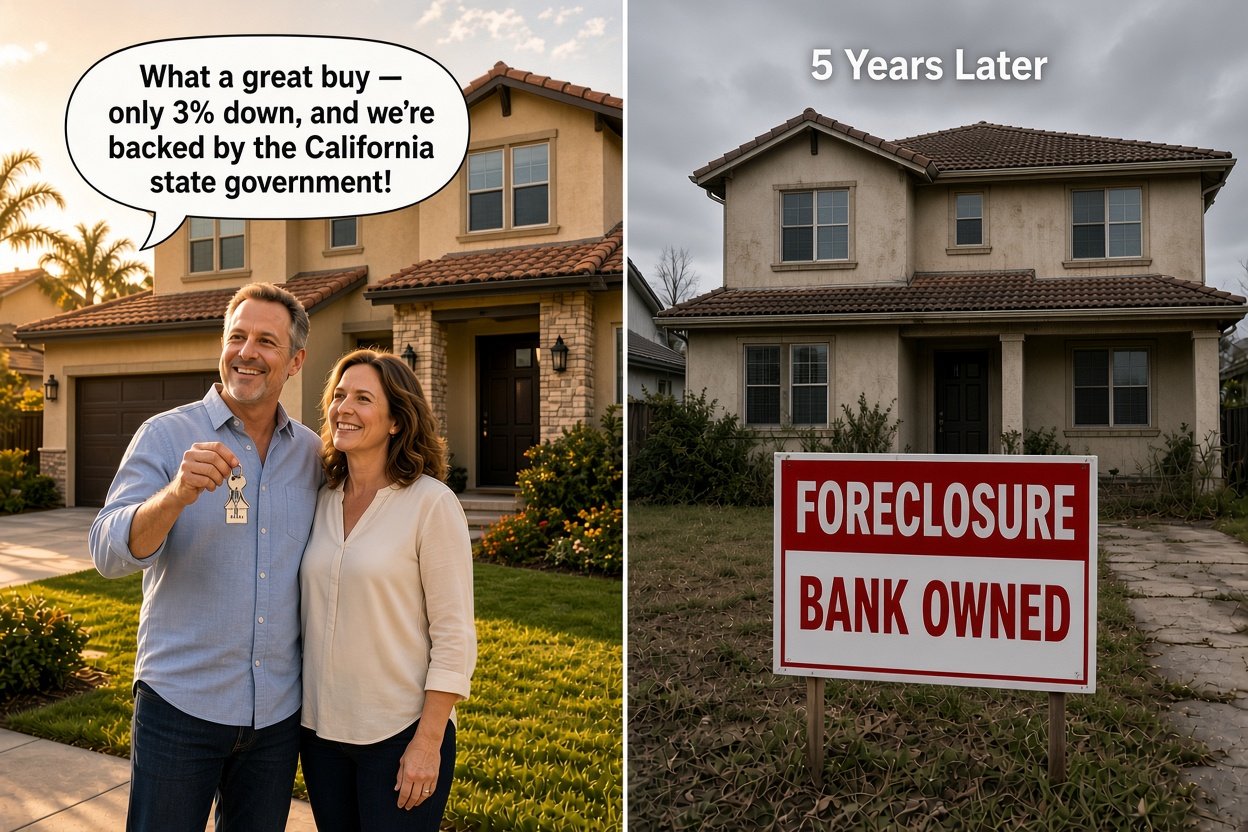
- The 3% Buyer Contribution: The homebuyer puts down a meager 3% of their own cash out of pocket.
- The 17% State Second Mortgage: The California Housing Finance Agency (CalHFA) steps in via a massive $25 billion revenue bond program to fund a second mortgage covering 17% of the purchase price.
- The 80% First Lien: Combined, the buyer’s 3% and the state’s 17% hit the magical 20% down payment mark, allowing the primary lender to write an 80% first mortgage and bypass traditional PMI requirements.
Sounds clever, right? Not so fast.
Unlike traditional PMI—which is a temporary monthly insurance fee that automatically drops off the moment your home equity hits 20% through market appreciation or amortization—this 17% state-funded second mortgage is real, hard debt. It requires an entirely separate, fixed monthly debt service payment alongside your primary mortgage, property taxes, and insurance.
If you hit a financial rough patch, you can’t simply call your lender and ask them to cancel your second mortgage. You are locked into a double-debt structure with a razor-thin equity cushion.
The Parallel to 2008: Stated Income and Zero-Cushion Lending
Let’s cast our minds back to the mid-2000s. Back then, lenders pushed “stated income” loans where borrowers could literally write down whatever salary they wanted on an application without verification. The justification from policymakers at the time? “We need to make housing accessible and democratic.”
We all know how that ended: a catastrophic cascade of foreclosures, collapsing financial institutions, and a global economic meltdown.
When you allow buyers to enter the California real estate market with only 3% of their own capital at risk, you eliminate the natural friction and financial discipline that protects the housing ecosystem. Traditional private mortgage insurers (companies like MGIC or Radian) act as strict commercial gatekeepers. They are private, for-profit entities with their own capital on the line, so they aggressively reject marginal files, high debt-to-income ratios, and risky underwriting.
Government-backed bond programs driven by political mandates, on the other hand, frequently prioritize volume and optics over sound underwriting. When qualification criteria shift to accommodate social engineering goals rather than pure creditworthiness, default risk skyrockets.
Who Is This Actually For? (Hint: Not You)
Let’s be entirely realistic about who benefits from a $25 billion demand-side stimulus directed exclusively at new construction and primary residences:
It is a custom-built bailout for large-scale California homebuilders.
When builders are sitting on massive inventories of newly constructed homes that everyday buyers cannot afford at prevailing interest rates and high sticker prices, injecting billions of dollars of subsidized state leverage into the market doesn’t lower home prices. Instead, it artificially props them up.
It acts as a price-maintenance scheme. The builders unload their inventory at peak valuations, the state issues billions in revenue bonds to finance the transactions, and the new homeowner steps into a highly leveraged property with zero equity buffer.
The Taxpayer Bailout Waiting in the Wings
Proponents of Prop 37 will quickly point out that these are revenue bonds, meaning they are legally structured to be repaid solely through the monthly loan payments made by participating homebuyers—not directly out of the state’s General Fund.
As seasoned real estate professionals know, legal classifications matter very little when macro-economic reality strikes.
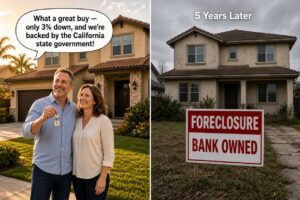
What happens if California experiences an economic slowdown, tech sector corrections, or a localized real estate downturn where home values drop by just 5% to 10%?
- Buyers who put down 3% cash instantly plunge into deep negative equity.
- Default rates across a massive state-backed bond portfolio begin to climb.
- The revenue streams drying up leave CalHFA’s reserves severely depleted.
When a public housing finance agency faces systemic defaults on a multi-billion-dollar portfolio, bondholders panic, credit ratings drop, and political pressure mounts on the California Legislature. Lawmakers will inevitably step in to “save the agency” and backstop the bondholders. In the end, the general public—the California taxpayer—eats the loss.
Conclusion: A Short-Term Sugar Rush with Long-Term Pain
Housing affordability in California is a genuine crisis, but manufacturing a synthetic housing boom by loading up low-equity buyers with double-barreled mortgage debt is a dangerous game.
Traditional low-down-payment loans survived the last decade because of rigorous post-2008 documentation and a relentless 10-year bull market in real estate appreciation that bailed out thin margins. Relying on perpetual appreciation to bail out 3%-down, state-subsidized buyers is a gamble that history proves will eventually fail.
When a state government steps in to replace a functioning private industry like California’s mortgage insurance sector, you have to ask why. The private PMI industry was stable and functioning precisely because it enforced stringent, merit-based rules to protect against default. By replacing those guardrails, this program appears designed to bypass traditional financial qualifications in favor of relaxed criteria (DEI)—shifting the focus away from a borrower’s proven capacity to repay. When lending standards are compromised for political or demographic objectives rather than strict financial capability, history shows the program is headed for disaster. Ultimately, it won’t be the politicians or the home builders who pay the price; it will be the everyday California taxpayers left holding the bag when the defaults roll in.
This program is a short-term sugar rush for California homebuilders and a long-term financial trap for unsuspecting buyers and taxpayers. If you’re looking at buying new construction in California under this program, look past the marketing hype, run your total debt service math, and ask yourself who is really carrying the risk when the market turns.
Disclaimer & Disclosure: This content is provided for general informational, educational, and entertainment purposes only and should not be construed as financial, legal, tax, or real estate investment advice. The views and opinions expressed herein do not constitute a recommendation or solicitation to buy, sell, or hold any security, financial instrument, or real estate property. Because financial markets, tax laws, and real estate regulations vary by jurisdiction and change constantly, you should always consult with qualified, licensed professionals—including a certified financial advisor, attorney, CPA, and licensed real estate broker—before making any financial, legal, tax, or investment decisions. No representations or warranties (express or implied) are made regarding the accuracy or completeness of this information, and the author and publisher assume no liability or responsibility for any actions taken or decisions made based on the content of this site. Additionally, this post may contain affiliate links; if you make a purchase or sign up through these links, we may earn a small commission at no additional cost to you.
The California Housing Bond Trap
#######
Brokerforyou.com is for SALE
- Just like most major businesses, the easiest way, and the fastest way to expand your business and influence in your particular market is through strategic acquisition. Just look at Google, they are the number one search engine in the world! Google bought Youtube in November 2006 for US$1.65 billion! YouTube now operates as one of Google’s subsidiaries.www.brokerforyou.com is for sale and is offered with a very popular San Diego residential real estate channel with 1.16K subscribers and 114 videos!!What’s the approximately monthly cost to host a website? With shared hosting, you’re hosting fee can break down to about 10 to $15 per month. To keep your url registered (that’s your site address), this is usually paid on a five to 10-year basis, which averages out to about just a dollar per month! Naturally, if you add direct hook-up to a MLS database, that provides lead capturing, this costs can vary greatly from provider-to-provider.
- Also available, much smaller aged websites (not just urls) for Real Estate agents and brokers in California. Yes, since I’m retired from Real Estate now I have a number of websites that are available that you can use for readings to your main site. The following real estate area sites are available but subject to prior sale, without notice: San Diego, downtown San Diego, Del Mar, Encinitas, Orange County, and Los Angeles. If you’d like to purchase any of these sites with all the content included, you can get them at a Bargain Basement price. Please contact me if you’d like further details.
- Interested: seo711@gmail.com for additional information
Looking for a real unique gift/Investment?
Natural gold nuggets

Natural gold nugget Visit our California & Arizona gold prospecting site.
+++++++++++++
Great 360 Camera – This is the one that I use not only for real estate but motorcycling & gold prospecting.
Direct from the manufacturer w/ Free shipping, special bonus accessory & even tax included.
Click camera photo below for more details and to see actual 360 video & photos taken with this amazing marvel, direct from manufacturer . . .

- insta360 One X3
++++++++
Disclaimer & Affiliate Disclosure
General Information & Personal Opinions
The content provided on this blog is for informational and educational purposes only and represents solely the personal opinions and observations of the author. It should not be construed as professional, legal, real estate, tax, or financial advice. Because every individual’s financial and personal situation is unique, you should never rely solely on the information presented here when making significant real estate, investment, or financial decisions. Before taking any action based on content from this site, always consult with a qualified financial advisor, CPA, real estate professional, and/or legal counsel.
Affiliate Advertising Disclosure
To help support the maintenance and operation of this blog, some of the links on this site may be affiliate links. This means that if you click on a link and make a purchase or sign up for a service, I may receive a modest affiliate commission at absolutely no additional cost to you. I only recommend products, services, and resources that I genuinely believe provide value to my reader